Q: Sri Lanka’s tax income has risen sharply lately. Has the nation reached some extent the place the emphasis ought to shift from elevating extra taxes to creating the present system work higher and fairer by taxpayers?
A: The nation has efficiently completed the income mobilisation section of its post-crisis restoration, and is now reaching the purpose the place the emphasis ought to more and more shift in the direction of bettering tax administration, compliance and equity.
The nation’s tax to GDP ratio has recovered considerably from disaster period ranges and authorities income efficiency has exceeded a number of IMF programme targets.
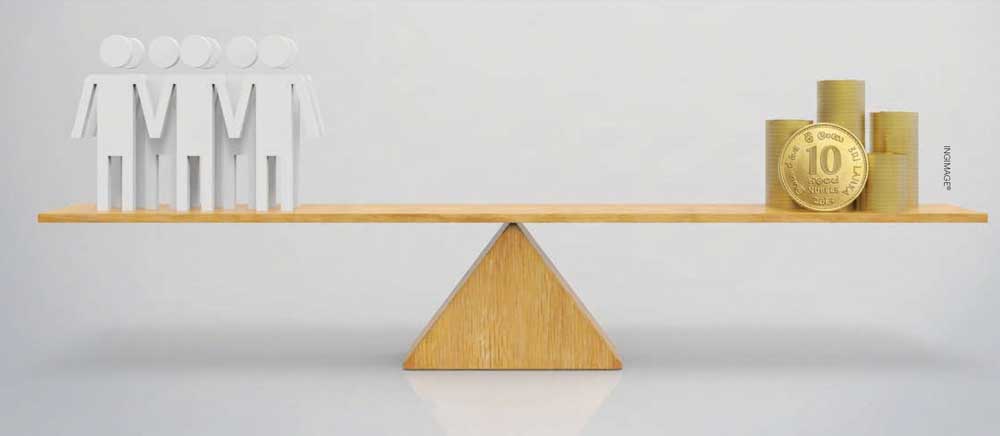
A lot of this enchancment has been pushed by VAT will increase, broader tax bases and stronger assortment efforts. The problem now could be guaranteeing that the burden is distributed extra equitably and the system encourages voluntary compliance moderately than relying totally on larger charges.
And the subsequent stage of reform ought to deal with increasing the tax base, lowering informality, bettering taxpayer providers, modernising Income Administration Administration Info System (RAMIS), accelerating refunds and dispute decision, and utilizing knowledge analytics to establish noncompliance.
The problem now could be guaranteeing that the burden is distributed extra equitably
Charmaine Tillekeratne
A effectively administered system that taxpayers belief is in the end extra sustainable than repeatedly growing charges on the identical compliant taxpayers.
Q: The clock now runs longer for VAT offences (to as many as 12 years) and penalties have been elevated by a median 40 instances, in line with some reviews. How do you view this situation?
A: The extension of the limitation interval to 12 years and the substantial improve in penalties replicate a transparent coverage determination to strengthen tax enforcement, and deter deliberate tax evasion.
Given the size of worth added tax fraud dangers and fraudulent refund claims internationally, the rationale for offering the Inland Income Division (IRD) with an extended enforcement window is comprehensible.
Nevertheless, the effectiveness of those measures will rely closely on how they’re utilized. Robust penalties are justified the place there’s fraud, concealment or wilful evasion.
Companies will nonetheless count on assurance that real errors, interpretation variations or system associated compliance failures aren’t handled in the identical manner as deliberate misconduct.
From a enterprise perspective, these amendments considerably improve compliance threat. Corporations ought to strengthen documentation, preserve VAT information for longer durations, assessment refund claims rigorously and guarantee inside controls are sturdy.
The message is evident: VAT compliance is now not a routine administrative train however a board degree governance concern.
Q: When worldwide buyers evaluate Sri Lanka with competing locations within the area, the place does the tax system assist us? And the place does it put Sri Lanka at an obstacle?
A: The nation’s tax system has a number of strengths that buyers worth.
It has a longtime treaty community, OECD aligned switch pricing guidelines, an Advance Pricing Settlement (APA) framework, focused funding incentives, and aggressive decrease price preparations for qualifying exports and cross border services.
Enhanced capital allowances might be claimed as a double deduction, which may find yourself with a tax loss – this can give extra years to assert such a loss and might be thought-about as one thing much like a tax holiday
These options present a comparatively refined tax structure in comparison with many rising markets.
The problem is just not often the structure however the execution.
Traders place a premium on certainty, predictability and administrative effectivity. Frequent legislative modifications, sluggish dispute decision processes, delays in refunds and perceptions of regulatory uncertainty can improve funding threat.
As well as, Sri Lanka’s customary company tax price of 30 p.c is larger than that of a number of competing jurisdictions in Asia.
In brief, Sri Lanka presents a technically credible tax framework however its competitiveness would enhance considerably by way of larger stability, administrative effectivity and coverage consistency.
Q: What would you say to critics of the tax regime who argue that taxpayers are bearing the brunt of administrative inefficiencies and gaps in implementing the tax legal guidelines?
A: The criticism has some benefit.
When assessments are delayed, and interpretations range amongst places of work and appeals take years to conclude, or refunds stay excellent for prolonged durations, taxpayers successfully bear prices that come up from administrative inefficiencies moderately than noncompliance.
That mentioned, the dialog shouldn’t be framed as ‘taxpayers versus the administration.’ A contemporary tax system requires accountability on either side. Taxpayers should adjust to their obligations whereas the administration should present readability, consistency, well timed steering and environment friendly service.
A effectively administered system that taxpayers belief is in the end extra sustainable than repeatedly growing charges on the identical compliant taxpayers
The optimistic improvement is that tax coverage reform is more and more being matched by tax administration reform.
Strengthening RAMIS, adopting knowledge analytics, transferring in the direction of prefilled returns, bettering taxpayer providers and modernising audit processes are all vital steps.
The last word goal ought to be a tax authority that’s not solely efficient in accumulating income but additionally predictable, transpalease and repair oriented.
Q: With VAT at 18 p.c, how is the present tax construction affecting the restaurant and hospitality sector – each by way of shopper demand and the price of doing enterprise?
A: The hospitality and restaurant sector faces stress from each the demand and price facet. Eating out is discretionary spending, making it extremely delicate to cost will increase.
An 18 p.c VAT atmosphere inevitably influences shopper behaviour, significantly amongst center revenue households whose budgets stay below stress following the financial disaster.
On the identical time, companies face rising working prices together with labour, utilities, meals inputs and financing bills.
Though registered companies can declare VAT credit, money circulation constraints stay a problem, significantly for smaller operators. Subsequently, many companies face a troublesome balancing act between sustaining affordability for purchasers and defending profitability.
The sector has demonstrated resilience particularly with the restoration of tourism however margins stay below stress. For a lot of operators, the problem is now not genescore income however sustaining sustainable profitability in a better price atmosphere.
Charmaine Tillekeratne is the Accomplice, Head of Tax of Deloitte Sri Lanka & Maldives.
