What it, nevertheless, chooses to disregard is the bigger fiscal and monetary self-discipline embodied in encouraging a majority price-sensitive society to maintain shifting in the direction of digital funds and a less-cash society. Such an argument would not account for the large financial savings made by RBI and banks in lowering printing of foreign money, and logistics of switch and upkeep of money.
Additionally Learn: UPI’s free lunch is over: Why the 0.4% MDR cost is truthful, wanted and overdue
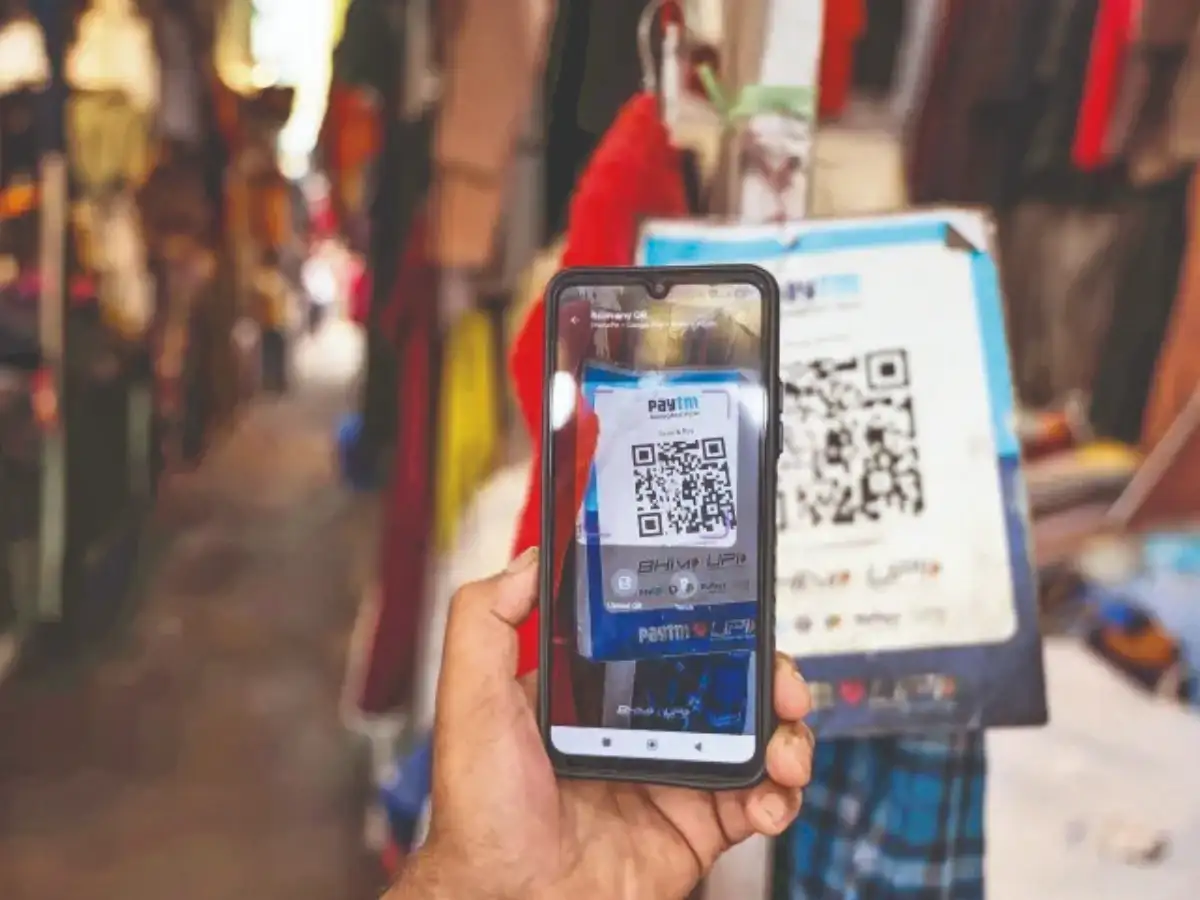
The top shopper is price-sensitive. After the newest MDR discover reached distributors, many eliminated the QR code show from their outlets fearing harassment by tax authorities. Many petrol pumps have reportedly already began to insist on cash-only cost. Many are even going again to debit/bank cards, to not point out money withdrawals from ATMs. The fig leaf of no expenses in UPI under ₹2,000 is just too small an quantity, and can result in ‘splitting’ of funds.
To maintain digital funds ‘incentivised’, the consensus needs to be that no fintech price be loaded to finish shoppers, however MDR bills be footed from financial institution financial savings. Charging the tip person, in reality, would ultimately usher in fiscal self-discipline by enhancing credit score scores.
Additionally Learn: Credit score the place credit score’s due: India’s tokenised bonds should now open the door to world capital
In 2012, government-to-person (G2P) welfare schemes accelerated after linking the bottom financial cohort of the inhabitants to monetary establishments, after which to digital switch by way of DBTs. That triggered a coverage to digitise submit places of work and cooperative banks that constituted 3/4th of economic establishments. There was a gradual linear climb of different modes like RTGS and NEFT operation throughout financial institution timing home windows.
RBI’s basis was set with RTGS and NEFT for digital clearings. Introduction of UPI in 2016, and deepening of digital cost efforts in 2019, ensured extra individuals shift to a mobile-based cost system, and transfer in the direction of smartphones even in rural and semi-rural India. 84% of digital funds have been high-frequency micro-payments by UPI with zero price to finish customers. This has made for 9% of worth, with most ticket measurement being lower than ₹2,000. Different modes the place there may be price, the tendency has been to shift to money.
Value to digital cost previous to MDR made zero in January 2020 was paid by retailers to banks and repair suppliers. P2P of UPI being free incentivised and enabled even small-ticket measurement to maneuver to digital funds. The fee was borne by GoI by budgetary provisions.
Positive, budgetary assist cannot be in perpetuity. However the reply would not lie in charging finish customers and triggering a shift to money. It lies in tapping the large financial savings made by RBI and monetary establishments like banks by the printing of much less foreign money, logistics and safety offered for the money with them.
0.3-0.5% MDR on transactions needs to be charged for transactions above ₹2,000, and an 1.1% interchange payment to pay as you go wallets. The reply would not lie in simply accounting for bills and charging the tip person, however to feed this cost elsewhere.
RBI printing expenditure fell to ₹4,875.2 cr in FY26 from ₹6,372.8 cr in FY25, a lower of 23.5% in only one 12 months as a consequence of digital funds’ exponential development. Absolutely the worth of foreign money in circulation has tripled from ₹15 lakh cr in 2016 to about ₹43 lakh cr in 2026, incentivised by taxation insurance policies and non-resorting to digital funds. The main target is to curb this tendency and encourage digital funds.
Establishments are focusing extra on monetary inclusion, encouraging account-to-account and digital funds, thereby lowering requirement of money significantly. It will additional come down by wholesale CBDT utilization. So, if India is severe about curbing the money float that escapes tax web, and lowering the parallel economic system, there’s a robust must rethink the newest transfer on the MDR entrance and never cost finish customers the costs for digital cost.
All insurance policies and steps ought to incentivise digital funds with the fintech expense invoice being supported by financial savings by RBI and banks by way of non-printing of currencies, offering safety and logistics. These will set off the continued unfold of digital cost and, on the similar time, be sure that fintech prices are met.
The author is former secretary, GoI
