Lately, Nepal has suffered each pure and man-made disasters. On August 26, Nepal was rocked by a flash flood that destroyed billions of {dollars}’ price of homes, hydropower crops, bridges, and automobiles in lower than a day. This occurred inside a yr of the September 2025 protests which was punctuated by widespread injury to buildings and auto-vehicles. These cases have raised the query: For a rustic always affected by disasters, why is insurance coverage not a much bigger a part of the chance administration discourse?
A continual lack of insurance coverage protection stays a vital concern in Nepal. Non-life insurance coverage, also referred to as basic insurance coverage, covers areas equivalent to auto and property. For creating economies, the extent of non-life insurance coverage penetration, which is a metric that reveals the relative dimension and financial significance of insurance coverage inside a nationwide financial system, is strongly correlated with constructive financial development.
Disasters, equivalent to local weather shocks, have had important impacts on Nepal’s financial system prior to now. The 2015 Gorkha earthquake resulted in USD 5.2 billion (NPR 806.08 billion) in damages and USD 1.9 billion (NPR 294.53 billion) in financial loss. Nevertheless, solely USD 210 million (NPR 22.68 billion) price of the broken properties had been insured. Non-life insurance coverage penetration, which is the same as complete gross premiums divided by Gross Home Product (GDP), did develop from 0.49% in 2015 to 0.58% in 2016, nonetheless the next annual development fee topped out at 0.04% till the COVID-19 pandemic in 2020. Since then, the penetration development fee has stagnated at 0.7%.
Sustainable financial improvement amid disasters is contingent upon a recalibration of the general public’s notion of, and entry to non-life insurance coverage. Altering this requires higher motion by regulators to pressure compliance from insurance coverage corporations.
Overview of the Nationwide Insurance coverage Sector
The non-life insurance coverage business in Nepal consists of 18 corporations, with 4 categorised as micro-insurers. In FY 2081/82 BS (FY 2024/25 AD), the whole quantity of insurance coverage premiums collected by these corporations amounted to NPR 43.94 billion (USD 283.93 million), a rise from NPR 29.82 billion (USD 192.69 million) in FY 2077/78 BS (FY 2020/21 AD) Probably the most important agency within the non-life sector is the Rastriya Beema Firm Restricted (RBCL), a state-owned insurance coverage agency with NPR 24.08 billion (USD 155.59 million) in complete property, as of FY 2081/82 BS (FY 2024/25 AD). RBCL additionally has the third-highest market capitalization worth of all insurance coverage corporations, life and non-life, listed on the Nepal Inventory Change (NEPSE), and has the third-highest share value of any NEPSE-listed firm.
Comparatively, the life insurance coverage sector collected NPR 182.17 billion (USD 1.17 billion) in premiums in FY 2081/82 BS (FY 2024/25 AD). For additional context, RBCL would solely be the 11th largest agency by complete property within the life sector which consists of 17 corporations, three of that are micro-insurers.
Misalignment of Insurance coverage Precedence
Nepal’s insurance coverage business possesses a major dichotomy between the life and non-life sectors.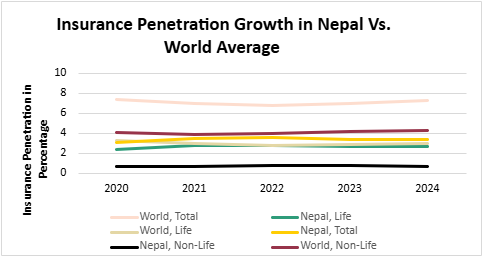
Determine 1. Insurance coverage Penetration and Development in Nepal Vs. World Common (Nepal Insurance coverage Authority Statistical Yearbook 2081/82 & Month-to-month Non-Life Insurance coverage Enterprise, Shrawan, 2083)
Nepal’s life insurance coverage penetration is aligned with the worldwide common of three.0% with solely a 0.3% distinction in 2024. Moreover, the worldwide common for non-life insurance coverage penetration mirrors that of its life counterpart. Nevertheless, Nepal’s non-life insurance coverage penetration is considerably decrease than the worldwide common at solely 0.7% in comparison with the worldwide common of 4.3%.
Furthermore, the non-life sector is skewed towards auto insurance coverage, reasonably than segments which are probably the most tough to rebuild following a catastrophe, equivalent to property.
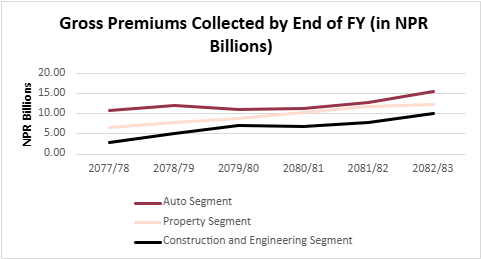
Determine 2. Gross Premiums Collected by Finish of FY (in NPR billions) (Nepal Insurance coverage Authority Statistical Yearbook 2081/82 & Month-to-month Non-Life Insurance coverage Enterprise, Shrawan, 2083)
Auto insurance coverage has dominated the non-life insurance coverage enterprise, however latest years have seen property insurance coverage starting to shut the hole, alongside a fast development in engineering and building insurance coverage. FY 2082/83 BS (FY 2025/26 AD) did expertise a widening of the hole; nonetheless, that’s attributed to heightened consciousness of car safety following the September 2025 protests.
The Core Components Perpetuating the Imbalance
The notion of non-life insurance coverage in Nepal is comparatively weak, with most small and medium-sized enterprises (SMEs) foregoing it of their operations as they view it as a luxurious, reasonably than a software for sustainability. That is attributable to the skinny revenue margins these corporations function with, yielding minimal extra capital expenditure past what’s required for day-to-day operations. This reluctance in participating with non-life insurance coverage extends to their private property, as nicely. As such, entrepreneurs as a substitute make use of non-robust coping methods, equivalent to financial savings or loans, when confronted with financial hardship caused by catastrophe. A standard false impression amongst SMEs is that insurance coverage is reserved for giant companies. That is attributable to a poor communication pipeline between insurance coverage corporations and entrepreneurs, in addition to a mismatch between the wants of SMEs and the insurance coverage merchandise on supply.
Moreover, public belief is undermined by the shortage of operational effectivity within the insurance coverage sector, as evidenced by the truth that, as of September 9, 2026, of the claims filed for affected property within the September 2025 protests, solely 38% have been settled. Per rules below the Insurance coverage Act, 2079, operators should comply with a specified timeline when responding to a declare. This course of is initiated upon the submission of a declare with the rapid appointment of a surveyor to evaluate damages, a 15-day restrict to conduct the evaluation, and the post-report payout inside three to 5 weeks. Monetary penalties are additionally levied on insurance coverage operators for arbitrary delays. The Non-Life Insurers’ Affiliation asserts that this determine will not be consultant of the scenario as most smaller claims have been settled and the determine is dragged down by the massive claims for which injury survey reviews have solely lately been submitted. Nonetheless, such a delay additional erodes the already restricted confidence entrepreneurs have for insurance coverage merchandise.
Latest Developments
There have been regulatory developments within the insurance coverage business in the previous few fiscal quarters, with actions taken by the Ministry of Finance (MoF), in addition to the Nepal Insurance coverage Authority (NIA). The MoF, in a bid of proactive threat administration technique, has paved the way in which for growth within the non-life insurance coverage sector by mandating insurance coverage for city constructing permits and transportation, growing the third-party legal responsibility protection from NPR 500,000 (USD 3230.88) to NPR 1 million (USD 6461.77), and increasing threat switch devices for catastrophe compensation and reconstruction. That is accompanied by the NIA issuing a directive in February mandating non-life insurers to formulate insurance coverage insurance policies based mostly on an index developed in-house that pre-determines the payout for injury attributable to climate and pure disasters. This monetary product is also referred to as parametric insurance coverage. This index should issue within the geographical construction which the property is situated in, the goal group taking out the coverage, and the specs of the climate and pure catastrophe dangers being insured towards.
The introduction of parametric insurance coverage gives most of the people with elevated transparency and predictability, which can improve non-life insurance coverage penetration assuming the general public is sufficiently knowledgeable of the adjustments. Nevertheless, regulation is simply as efficient as its enforcement, which the post-September dilemma has demonstrated is weak within the present atmosphere. Moreover, as of October 4, 2026, solely Shikhar Insurance coverage Firm Restricted and Sagarmatha Lumbini Insurance coverage Firm Restricted have rolled out parametric insurance coverage merchandise.
Method Forward
With Nepal’s vulnerabilities to pure disasters, significantly for households and Micro, Small and Medium-sized Enterprises (MSMEs), state actors should not merely move laws, but in addition implement compliance through strict regulation and supervision. Most of the people have to be satisfied of the advantages of non-life insurance coverage along with trusting that the premiums they pay will really yield safety and compensation when damages happen.
A rustic’s insurance coverage penetration is a robust basic proxy of financial robustness, significantly for a creating nation whose residents have lighter financial savings and fewer monetary sophistication. Insurance coverage is the hedge for pure disasters, and Nepal should prioritize connecting its individuals with this threat administration software if it seeks to attain defend its individuals and property.
